
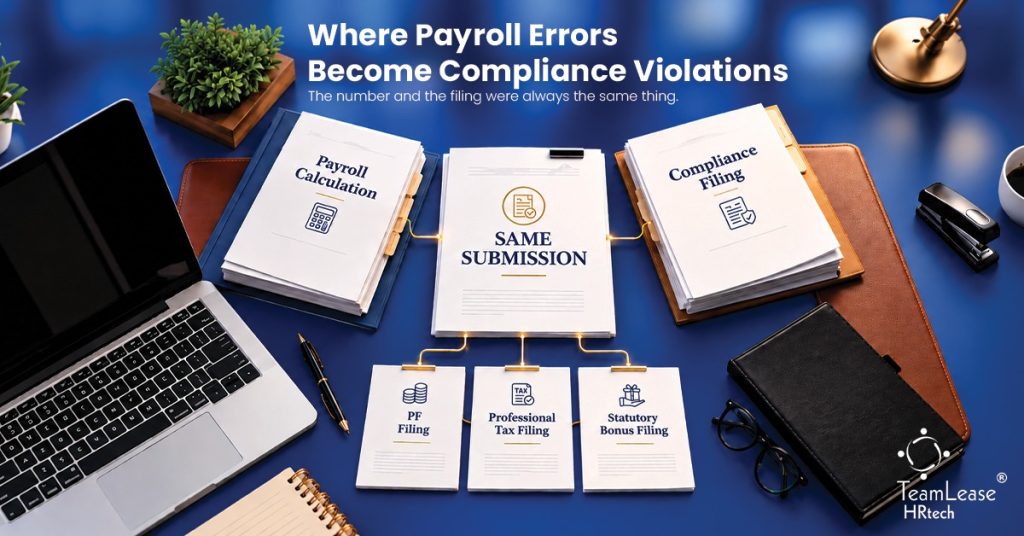
Payroll errors are treated by most companies as internal, correctable mistakes, and a compliance violation as a separate, more serious one. However, for a specific set of India’s statutory obligations—provident fund, professional tax, statutory bonus—that distinction doesn’t hold, because the calculation and the filing are the same submission. What companies need is a single accountable partner who owns both payroll and compliance, so that such errors don’t creep in.
Ask a finance leader what happens when an error creeps into payroll, and the answer is usually calm: it gets caught and corrected in the next cycle. Ask about a compliance violation, and the tone changes—that’s a different conversation, with different stakes, often reviewed at a different meeting altogether.
Most organisations manage their payroll and compliance risk thinking exactly like that. Payroll sits with finance operations. Compliance sits with legal, HR, or an outside specialist. It’s a reasonable way to think about most payroll processes and most compliance obligations, because for most of them, that separation genuinely reflects two different processes happening at two different points in time.
However, it’s wrong to think that way for all payroll processes. For several of India’s core statutory obligations—provident fund, professional tax, statutory bonus—payroll doesn’t produce a number that compliance later checks. Payroll produces the number that gets filed. There is no second team reviewing it before it becomes an official position with a regulator, no gap where a mistake sits quietly waiting to be caught. The calculation and the compliance event aren’t two steps in a sequence. For these categories, they are the same submission, made once.
This isn’t an exaggeration. It’s a description of how the filing actually works, and it changes what “catching a payroll error early” is supposed to mean.
Where the Filing Starts
Three categories make the point without needing a regulatory deep-dive to see it.
A provident fund contribution is calculated once, and that calculation is what gets remitted and filed—there’s no intermediate step where a wrong number is caught before it reaches the regulator. A professional tax deduction works the same way, state by state: what payroll deducts is what gets reported to the state authority, on that state’s own schedule. A statutory bonus is calculated annually against eligibility and surplus rules, and that same calculation is what the annual return records as paid.
Compare that with an ordinary payroll error—a wrong allowance, a missed deduction for a loan repayment. Someone usually notices before the next payslip goes out, because there’s a natural checkpoint: an employee queries a number, a manager reviews an exception report, finance reconciles before close. That checkpoint is exactly what’s missing for PF, PT, and statutory bonus.
A wrong PF contribution, a miscalculated PT deduction, or an incorrect bonus figure isn’t a payslip problem sitting quietly until someone notices it. The moment the filing goes out, these payroll errors stop being an internal matter. It’s a position on record with a government department, with its own clock ticking. From that point, interest and penalties start accruing, and in serious cases, personal liability follows for whoever signed off on the filing.
Two Owners, One Blind Spot
If the mechanism is this direct, why does it stay invisible until an audit or a notice surfaces it? Because almost no organisation is set up to see it in any other way.
Payroll typically reports through finance operations. Compliance typically sits with legal, HR, or a separate vendor entirely—sometimes literally a different company. Each side has its own priorities, its own cadence, its own definition of done. Payroll’s job is finished when salaries go out clean and on time. Compliance’s job is finished when filings are made and records stay current. Both teams can be doing their jobs well, by their own measures, at the exact moment an error crosses from one side to the other unnoticed. Nobody’s job description includes watching that specific handoff.
The result is that these errors are usually found late, and found by someone outside either team. An inspector flags a discrepancy during a routine audit. A regulator’s system throws up a mismatch. What was, at the point of calculation, a single wrong number is now a query that lands on a CFO’s desk with a filing date attached to it, a paper trail, and a question about how long it’s been happening.
The gap between when the error was made and when it surfaces isn’t a grace period. It’s a stretch of time during which the exposure has been quietly compounding, uncorrected, because nobody watching the payroll side had reason to look for it, and nobody watching the compliance side had reason to suspect the number itself.
This isn’t a story about carelessness. It’s a story about design. Splitting payroll and compliance ownership was a reasonable way to organise HR and finance work when payroll accuracy and compliance accuracy were, in fact, loosely coupled concerns. For PF, PT, and statutory bonus, they aren’t loosely coupled. They’re the same event, described twice, owned by two people who each only see their half of it.
One Pipeline, Not Two
Once the calculation and the filing are recognised as the same event, the fix stops being “communicate better between two teams” and starts being “make one team accountable for both.” A faster escalation path between payroll and compliance is an improvement. It isn’t a solution, because it still treats the translation from number to filing as a handoff that can go wrong, rather than a single step that should never have been split in the first place.
TeamLease HRtech’s managed payroll and compliance services are structured for that reality, not around the organisation chart most companies default to. Payroll runs through a documented cycle—input scrutiny, pre-payroll checks, processing, post-payroll checks—with variance reporting built in at each stage, so payroll errors that move a number unexpectedly between cycles get flagged before they reach a filing, not after they’re already on record.
Statutory deduction rate mapping is aimed at exactly the failure this piece has been describing: a PF, PT, or bonus figure calculated on the wrong basis, caught at the point of calculation rather than at the point of audit. And because compliance sits inside the same team rather than downstream of it, status is visible on a running dashboard rather than reconstructed after the fact, so there’s no gap left for an inspector or a regulator’s system to fill in first.
It’s one pipeline, one point of accountability, for a set of obligations that were never really two problems to begin with. The number and the filing were always the same thing. The only real question was whether one team would be accountable for both, or whether two teams would keep discovering that fact separately, after it was already too late to matter.
